
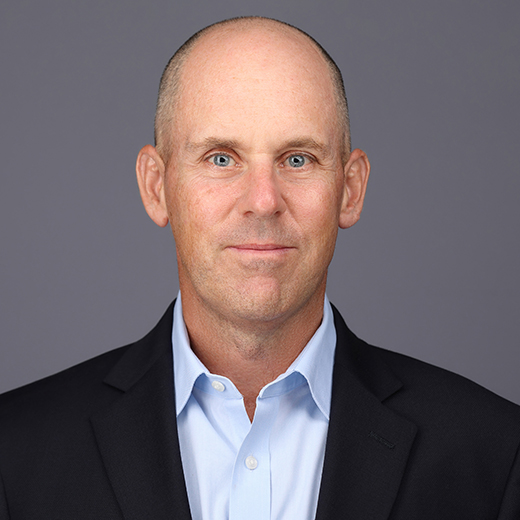
Jim Campasano studies empirical asset pricing with a focus on options. Currently he is examining how the term structure of implied volatility impacts the pricing and returns of equities and equity options.
Selected publication
- Simon, David P., and Jim Campasano. “The VIX futures basis: Evidence and trading strategies.” The Journal of Derivatives 21, no. 3 (2014): 54-69.
- Jim Campasano. “Portfolio Strategies for Volatility Investing.” The Journal of Alternative Investments 24, no. 1 (2021): 43-60.
- Jim Campasano. “Mitigating Risk with Conditional Option Strategies.” Forthcoming in The Journal of Alternative Investments.
Research & teaching interests
Jim Campasano's research and teaching focus on modeling, investments, and empirical asset pricing, with an emphasis on options.
Industry & academic experience
Prior to Northeastern, Campasano was an assistant professor at Kansas State University. Before entering academia, Campasano worked as an options trader on the sell side and a portfolio manager for multi-strategy hedge funds.
